This Week in Asia #46
Thai FMCG company Neo reported higher Q2 profits, partly helped by lower input costs. Korean index provider FnGuide upgraded its return-on-equity target from 18% to 30%. Indonesian paint maker Avia Avian stayed out of the sale of AkzoNobel's Southeast Asian unit, which went to Nippon Paint for US$1.35 billion.
Watchlist update
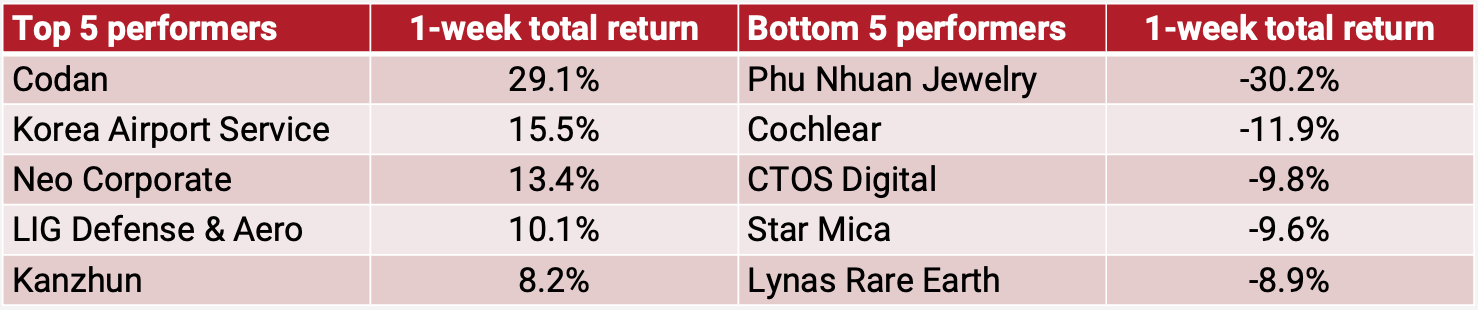
- Thailand's Neo reported strong Q2 results recently, with revenue up 18% and net profit up 161% year-on-year. Neo is a broken IPO that makes FMCG products like detergents sold in Thailand and Vietnam. The forward P/E ratio is now 11x. According to brokerage firm KGI, monthly sales growth has been around 20%. It has also benefited from falling input costs, which may or may not persist.
- Malaysian credit bureau CTOS Digital reported a cyber breach on 23 September, and the stock has taken a big hit over the past two weeks. It concerned the consumer-facing part of the business, but with no material financial impact on the operations. The stock now trades at a forward P/E of 13x.
- Korean index provider FnGuide updated its value-up plan to a very aggressive 30% return on equity, 20% compound annual growth in revenues and 40% capital returns. This is a massive jump from the previous 18% return-on-equity target.
- Another important news story for Avia Avian is that AkzoNobel's Southeast Asian unit will be sold to Nippon Paint for US$1.35 billion. I had originally hoped Avia Avian could buy the Indonesian subsidiary to consolidate the market. On the other hand, 16x forward EBITDA was a hefty price to pay, especially given Avia's own 6x EV/EBITDA valuation. So perhaps it was best that Avia stayed on the sidelines.
- There was another big insider buy in Indonesian conglomerate Astra International. President Director Rudy bought US$1.2 million worth of shares on the open market. The first-half 2026 earnings result wasn't great, with reported net profit down 19% year-on-year due to weakness in the mining segment. Note that Astra recently introduced a new management incentive scheme that emphasizes total shareholder returns. Astra now trades at 6x P/E. The problem with Astra's auto segment is heavy competition from Chinese EV maker BYD.
Worth your time
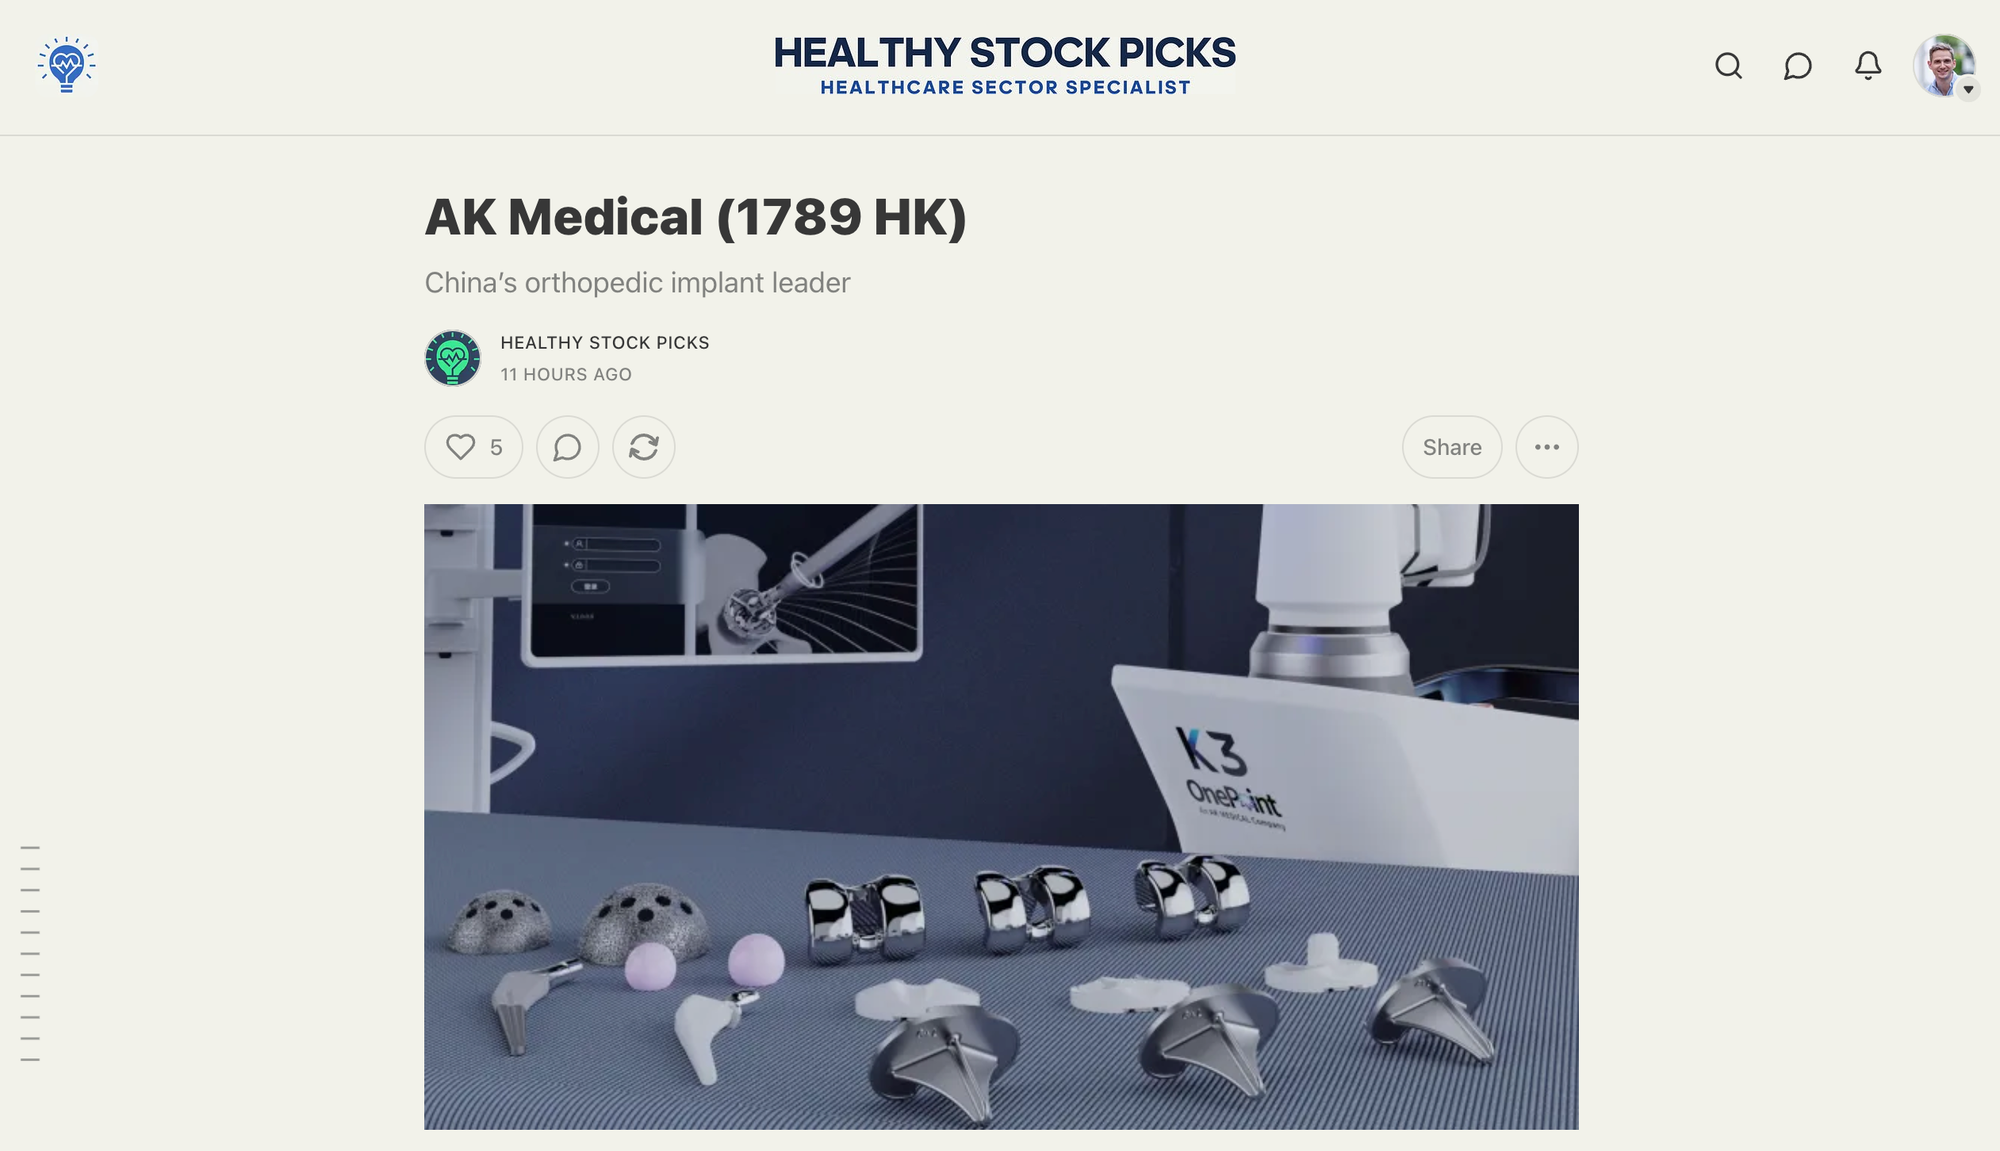
- The highlight of the week was Healthy Stock Picks' write-up on AK Medical, which saw insider buying back in July. AK Medical is a Chinese maker of hip and knee implants. It's been hurt by China's volume-based procurement policy, which put pressure on AK Medical's average selling prices. But the demographics are strong; AK Medical is growing rapidly overseas, and it also has a robotic system called K3+ that received regulatory clearance in January 2026. The stock trades at 10x P/E with a net-cash balance sheet. What makes me worried about AK Medical is its heavy buying and selling of wealth management products.
- I really enjoyed Ian Bezek's latest book reviews (Part 1, Part 2). They discuss Alex Gurevich's The Next Perfect Trade, which argued that government bonds were the perfect trade. The post-COVID period proved him wrong, but Ian thinks that bond yields have become attractive again. Another book mentioned is Generation Desperation, about how a journalist in the 20s tries to make money using a Robinhood account. It's a story of how retail investors tend to fail in the markets due to what could best be described as "vibe investing". I agree with Ian that 1929 wasn't a particularly enjoyable book to read.
- Finally, Tomas Pueyo's geographical analysis of Japan's history was great. He thinks that Japan's high mountains caused feudalism and led to the need for samurai. Firearms helped Japan unify but at the cost of repression and isolation from the rest of the world. Commodore Perry's arrival led to the Meiji Restoration and eventually Japan's modernization.
September 2026 portfolio update
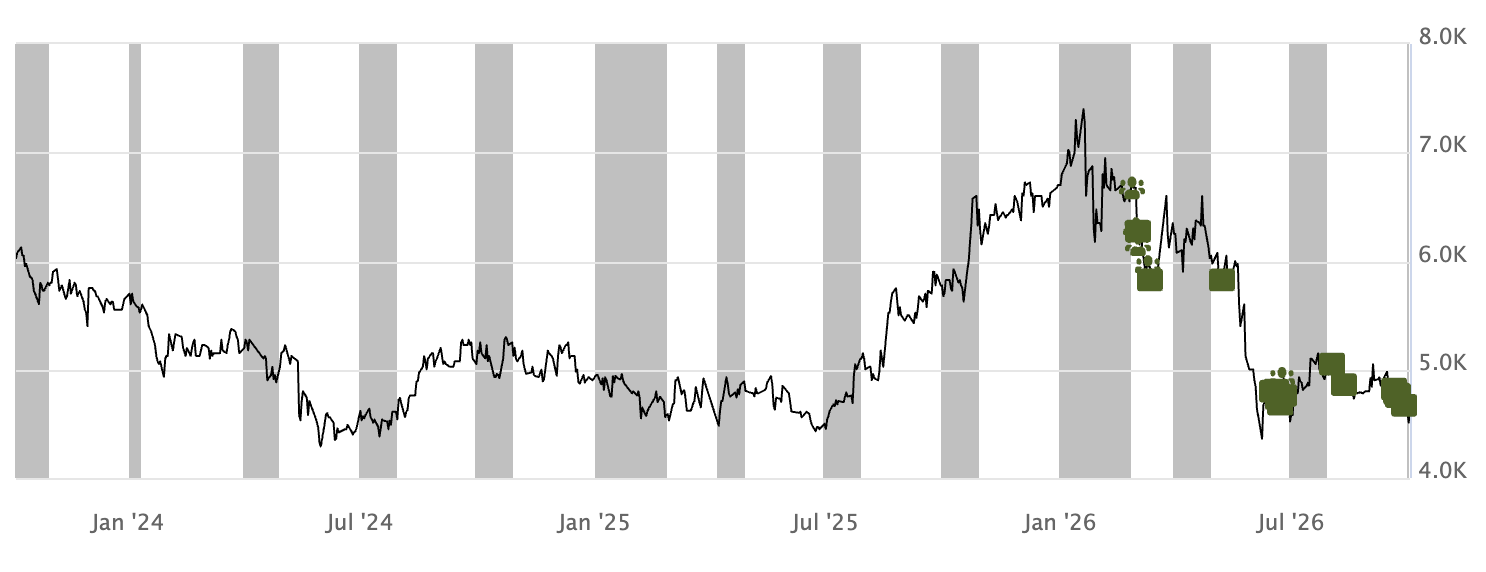
I do portfolio updates once a month, and the latest one discussed a few new purchases. I'm still on the sidelines with regard to botox maker Hugel.
You can read the full post here:
Portfolio update September 2026
Asian tourism, smart locks and Philippine IPOs
 Michael Fritzell

Get instant access to 150+ deep-dives on Asian value stocks:
Disclaimer: This post reflects my personal opinions and is for informational purposes only. It is not financial advice and not a recommendation to buy or sell any security, and it does not take into account your objectives, financial situation, or needs. I am not a licensed financial adviser in Singapore or anywhere else, and I don't give personalized advice — including in the comments. As of 5 October 2026, I own shares in Avia Avian but none of the other securities mentioned in this post or in the linked third-party articles. My other holdings are discussed in the linked September portfolio update. I receive no compensation from any company, fund, platform, publication or individual mentioned or linked in this post. My revenue comes solely from reader subscriptions. People I quote or interview may hold positions in the securities they discuss, may operate paid research products of their own, and I don't independently verify their claims. Where past performance is mentioned, it is not indicative of future results. Do your own research and consult a licensed financial adviser before making any investment decision. Michael Fritzell, published by Delante Media Pte Ltd.