This Week in Asia #44
Air Water + Lion Rock + Hugel
This is a free-to-read edition of Asian Century Stocks – a newsletter about Asian value stocks. New to the publication? Sign up here. If you don't want to receive these free weekly updates, you can adjust your e-mail preferences here.
Air Water has confirmed it's putting several major subsidiaries up for sale, making a near-term restructuring more likely. Lion Rock completed its OPUS acquisition. And I finally finished my deep-dive into Korean botox maker Hugel – a company that's now expanding into the US.
Watchlist update
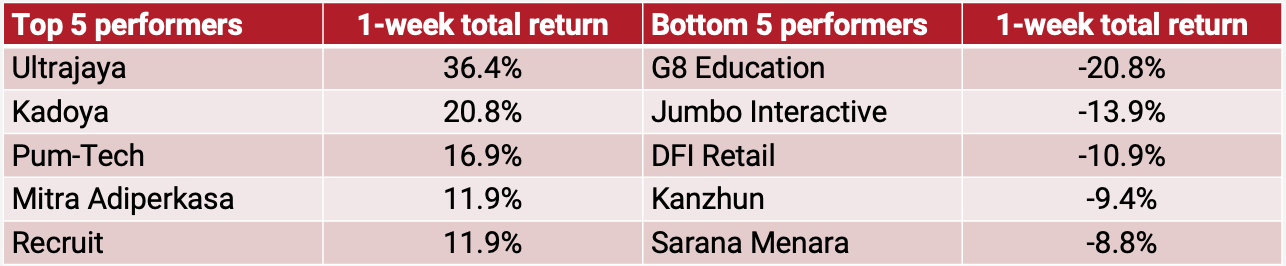
- The big story in Indonesia this week is that milk producer Ultrajaya acquired competitor Frisian Flag Indonesia for US$821 million through new share issuance. Frisian Flag's parent company, FrieslandCampina, will then become Ultrajaya's new controlling shareholder and must launch a tender offer for the public float, explaining the jump in Ultrajaya's share price.
- Air Water has earmarked several subsidiaries (combined revenue of JPY 250 billion) for sale, calling for a prompt divestment. It's now refocusing capital on its core industrial gas franchise, especially within the semiconductor industry, as well as in India and North America. The FY2030 target is a return on equity above 10%, which sounds conservative but okay. (Full disclosure: I own shares in Air Water.)
- Chinese engine maker Weichai Power, which Maius Partners wrote about here, jumped on the news that its customer Generac has signed a US$2.4 billion generator-supply agreement with Amazon. The key here is that Generac's generator line uses Weichai's Baudouin M55 engine platform, so Weichai should benefit from the deal.
- Meanwhile, Hong Kong's Lion Rock reported that it had completed its acquisition of OPUS from its separately listed subsidiary Left Field Printing. Expect the deal to be earnings accretive, showing up in the second-half 2026 result. (Full disclosure: I own shares in Lion Rock.)
- Insider buying in Asia has been very limited over the past week. However, the CEO of Korean used-car retailer K Car bought close to US$200,000 worth of shares. K Car buys used vehicles from car owners, inspects them, and then sells them to third-party dealers and exporters. K Car had a terribly weak second-quarter result, with revenues down -28% year-on-year, partly due to the conflict in the Middle East and record bonuses to staff as KG Group took over as a new shareholder. On a trailing basis, the stock trades at 7x P/E and a 15% dividend yield, but I'm not sure whether this yield is sustainable.
Worth your time
- Simeon McMillan came on the Yet Another Value Podcast to discuss Nintendo. He's one of the few bears who thinks Nintendo doesn't have a flywheel like Disney's. It's reliant on the hardware cycle and has been hit by high DRAM prices. He thinks Nintendo is too reliant on old intellectual properties such as Ocarina of Time, which mostly appeal to an older demographic. The number of Nintendo Switch Online subscribers has been flat for years. I somewhat agree with him, but some of those issues are temporary. (Full disclosure: I own shares in Nintendo.)
- Philipp Haas wrote about Japanese fan club operator m-up, the same stock that was written up on Value Investors Club earlier this year. m-up runs fan clubs for over 800 Japanese artists and makes money through 3.8m+ subscriptions. It's a highly profitable and growing business with a 35% return on equity. I've always wondered why others can't replicate the business, but I suspect founder Koichiro Mito's industry connections might be m-up's secret sauce. The stock trades at 21x P/E.
- JPARCVUE wrote up Japanese SaaS company Sansan. Its legacy business is digitizing business cards into a shared database that companies subscribe to. I've long felt that using physical business cards should be a thing of the past, but the practice persists in Japan. What's more interesting is Sansan's invoice management system, Bill One, which has become an industry standard. Sansan also runs a contract management system. The stock trades at an EV/Sales of 3.7x, broadly in line with its peer group. Its results for FY2026 ending in May 2026 were strong, with +24% revenue growth.
- Our friends at Smoak found a Korean stock that I've frankly never heard of before. The stock in question is Flitto, a provider of language training data for generative AI models. You might think that all data can be scraped, but tech giants are increasingly cautious about the data they use to train their models. Flitto has datasets for non-Western languages built over 14 years from 14 million users. Smoak believes that Flitto trades at 8.7x forward P/E on their 2026 estimate.
Hugel
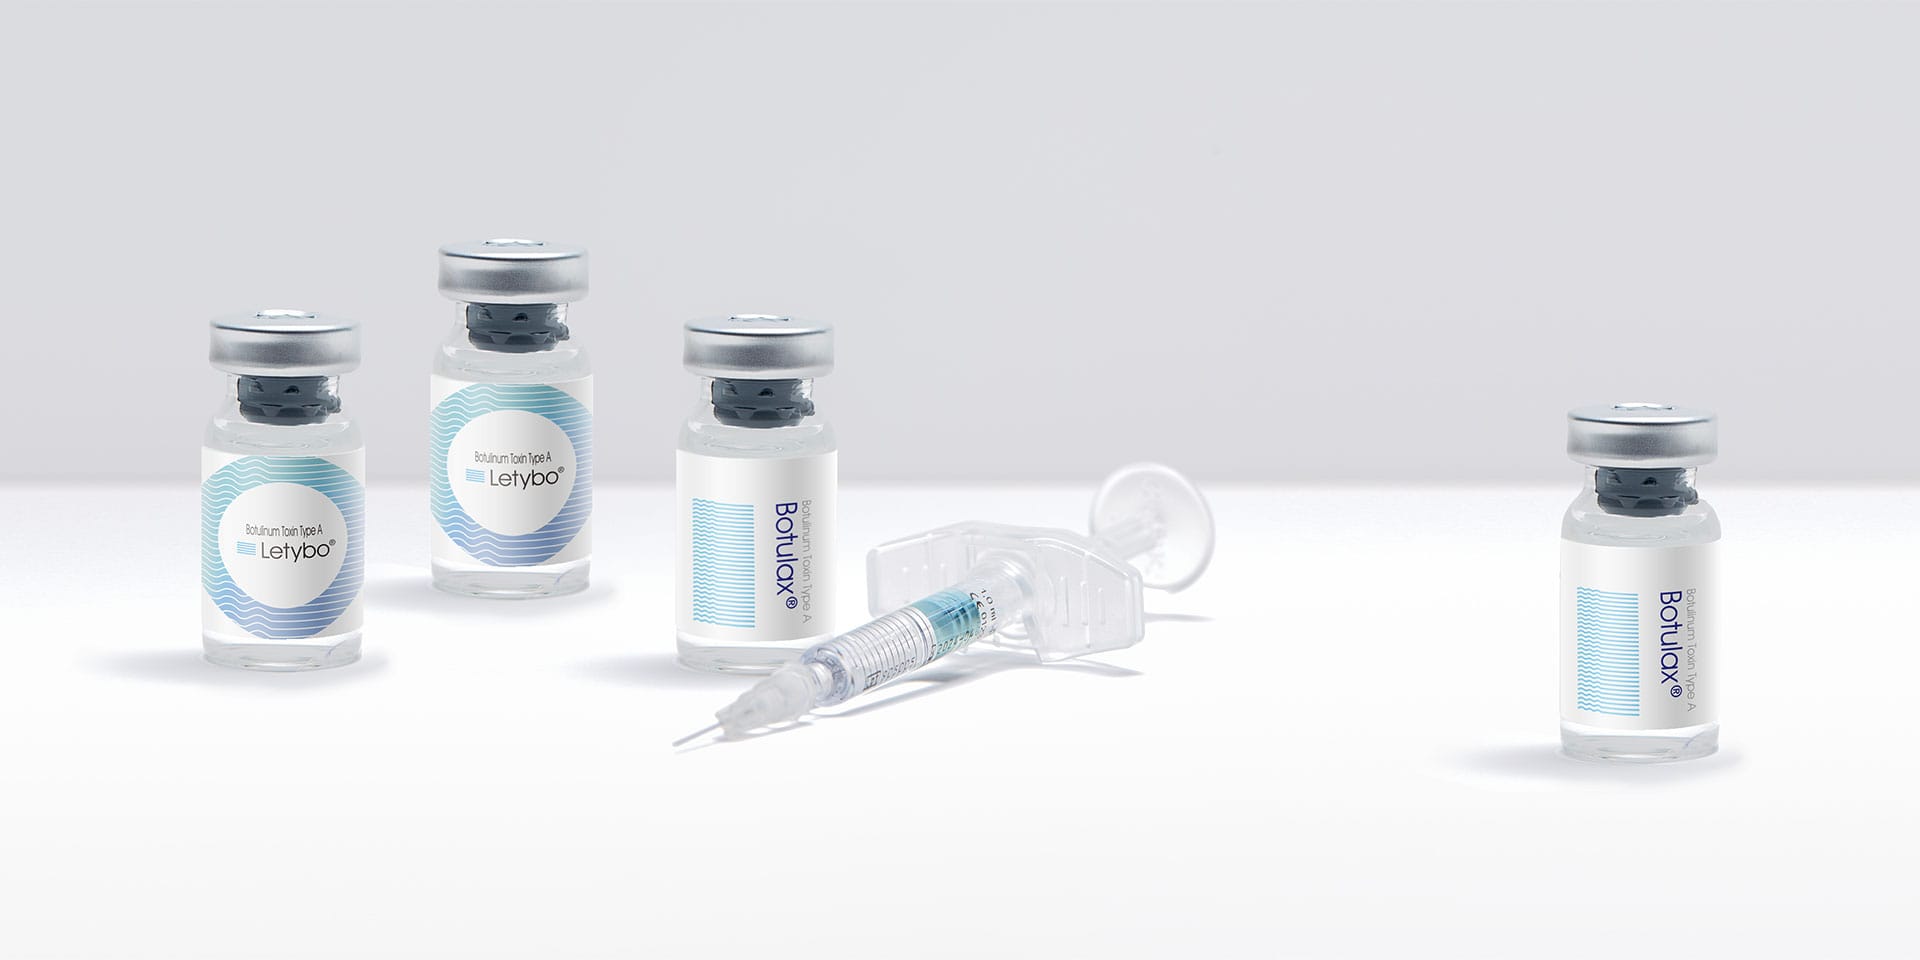
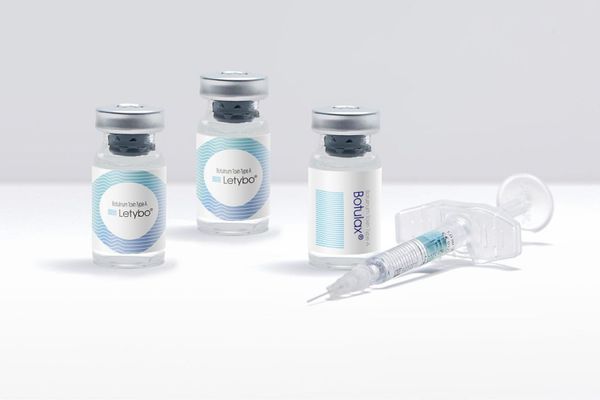
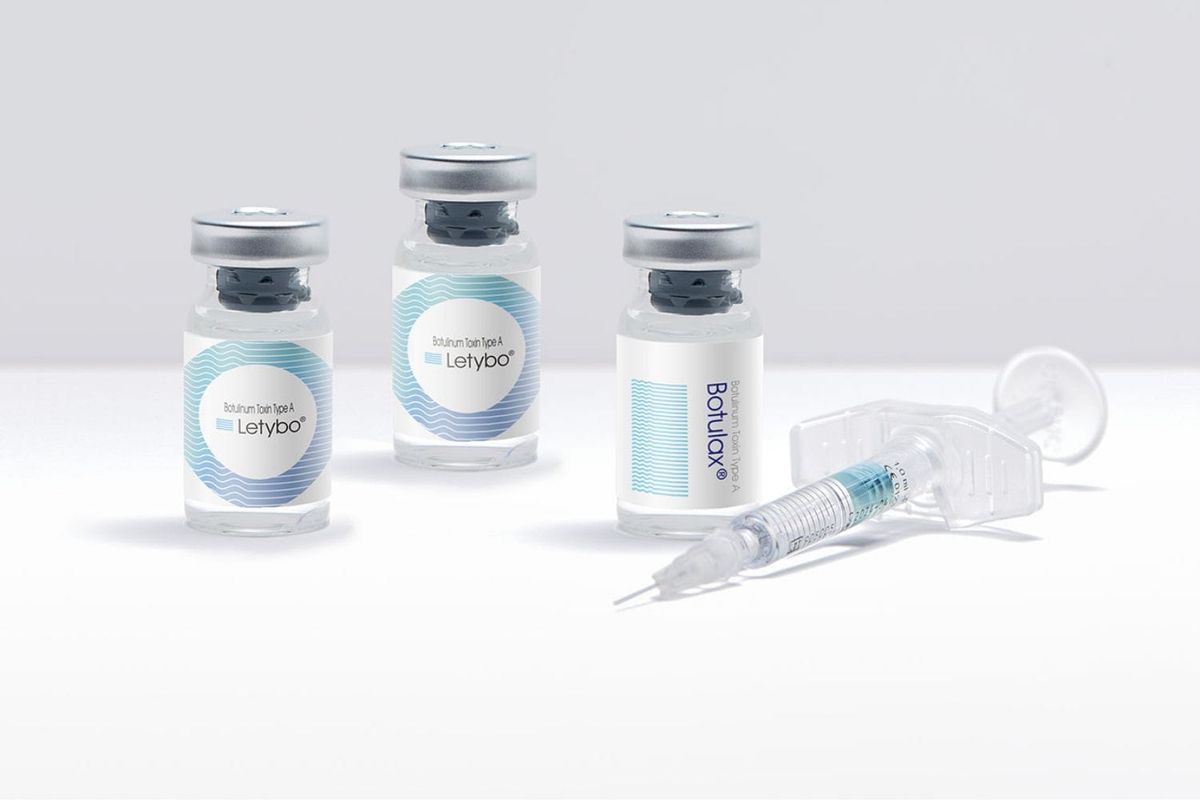
Yesterday, I published a deep-dive on South Korean botox maker Hugel. The company dominates the Korean market with over 40% market share. With regulatory approvals to sell its botox in the United States, the company is now ramping up its presence stateside through its new global CEO, Carrie Strom.
You can read the full deep-dive here:
 Michael Fritzell

Get instant access to 151 deep-dives on Asian value stocks: